

Outsourced bookkeeping for CPA firms means assigning routine, process-driven accounting production (reconciliations, transaction categorisation, AP/AR support and month-end close preparation) to an external team, while the CPA firm keeps the client relationship, the final review and professional responsibility.
Key takeaways
- Outsource the production (entry, categorisation, reconciliation, cleanup). Keep the judgement (review, sign-off, tax strategy, client advice).
- The driver is usually capacity, not cost. The US Bureau of Labor Statistics (BLS) projects employment of bookkeeping, accounting and auditing clerks to decline 6% from 2025 to 2035, so hiring for routine work keeps getting harder.
- Settle security and disclosure first. Check the AICPA confidentiality rules, your state board’s requirements, IRS Publication 4557 and your engagement letters before any client data moves.
- Compare total cost, not rates: the outsourcing fee plus your review time, management time and rework, against a fully loaded in-house hire (about $72,400 a year at the BLS median wage).
- Start with a four-week pilot on a few clients with clean, documented books. Measure accuracy, turnaround and rework before scaling.
- White-label means the provider works under your brand and in your software. It does not remove your duty to tell clients that a third party may access their data.
Why CPA firms are asking this question
Picture a managing partner on a Monday morning: three clients waiting on reconciliations, a senior accountant out sick, two new bookkeeping engagements just started. None of that work is strategic, and all of it crowds out the advisory work clients would pay more for, such as cash flow forecasting.
Outsourcing bookkeeping does not mean giving away control of client relationships. It means moving execution-heavy work to a specialised team so your professionals can focus on review, judgement and advice.
What is outsourced bookkeeping for CPA firms?
Most firms handle the same monthly bookkeeping work: bank and credit-card reconciliations, transaction categorisation, accounts payable and receivable, journal entries, financial statements, cleanup projects and month-end close. Split that list into work that needs CPA-level judgement and work that needs skilled, repeatable execution. The second group is usually much bigger.
Outsourcing assigns that second group to an external team. The team may be onshore, nearshore or offshore, and may work as a dedicated extension of your firm or through a managed service.
In the profession, this broader category is often called Client Accounting Services (CAS). Many providers, job postings and industry surveys use “CAS” and “outsourced bookkeeping” interchangeably, so it helps to know both terms when you research vendors.
What bookkeeping tasks can a CPA firm outsource?
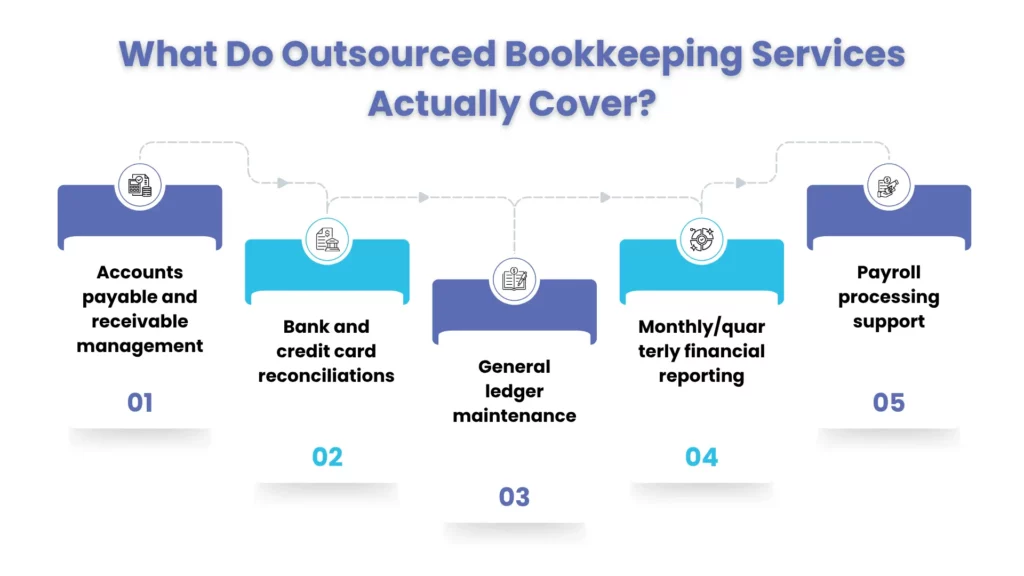
You do not have to outsource everything. A practical starting point is work that consumes many hours without needing your highest level of judgement.
| Work | What the outsourced team does | What your firm keeps |
|---|---|---|
| Transaction processing | Records and categorises transactions; works bank feeds and card activity under your documented rules | Approves the chart of accounts and categorisation rules; reviews exceptions |
| Reconciliations | Reconciles bank and card accounts by an agreed business day (for example, day 5) and flags unreconciled items | Reviews flagged items and signs off |
| AP and AR support | Processes invoices, records payments, tracks receivables | Approves payments and sets control policy |
| Month-end and year-end close | Prepares reconciliations, adjustments and draft financial statements | Reviews, adjusts and issues the statements |
| Cleanup and catch-up | Works through historical transactions against a defined cleanup plan | Decides scope and reviews opening balances |
Many teams now pair human review with AI-assisted categorisation and OCR receipt capture. Automation handles the volume, but a named reviewer still owns the accuracy of exceptions and unusual items. Corient’s outsourced accounting and bookkeeping service includes daily transaction processing and reconciliations, with teams trained on client-specific processes and software.
What your firm always keeps
Some work stays with you, whichever provider you choose:
- Final review and sign-off on financial statements
- Client communication and the engagement letter
- Tax strategy, tax return sign-off and advisory judgement
- Professional responsibility for the work product and for client data
- The decision on what gets outsourced, and to whom
Why CPA firms outsource bookkeeping
Your firm may not have a bookkeeping problem. It may have a capacity problem.
The BLS projects that employment of bookkeeping, accounting and auditing clerks will decline 6% from 2025 to 2035. Instead of competing for every hire, a firm can combine internal professionals with an external production team.
Five pressures usually sit behind the decision:
- Capacity: more clients means more transaction-level work.
- Hiring: recruiting and keeping bookkeeping staff slows growth.
- Seasonality: workloads spike around deadlines, which is where a tax season staffing plan pays off.
- Margins: routine production consumes billable professionals’ time.
- Growth: you need capacity before you need another layer of management.
Signs your firm is ready to outsource
- You are turning away referrals because the team is at capacity.
- Senior staff spend the first weeks of busy season fixing last year’s bookkeeping errors.
- Your best people are burning out.
- Client financials regularly arrive after the 20th of the month.
- Growth has stalled because you cannot hire locally fast enough.
If two or more of these sound familiar, the next step is a scoped conversation with a provider, not another round of searching.
Outsourced vs. in-house bookkeeping
Most firms end up with a hybrid, but the trade-offs look like this:
| Factor | In-house | Outsourced |
|---|---|---|
| Speed to scale | Hire and train for each new person | Capacity can typically flex within weeks |
| Cost structure | Fixed, year-round | Can scale down in slower months |
| Client knowledge | Builds faster | Needs documented processes to close the gap |
| Oversight | Management time | Vendor management plus review time (different, not necessarily less) |
| Continuity | Gaps during absence and turnover | Team-based cover |
| Best fit | Stable, predictable volume and a hiring budget | Uneven or growing volume with hiring constraints |
The cost section below shows how to put numbers on this comparison.
How outsourced bookkeeping works: a four-step model
Do not start by sending hundreds of client files to an unknown provider. Build the process first.
1. Define the work in measurable terms. Replace “handle bookkeeping” with specifics: reconcile bank accounts by the fifth business day, categorise to the approved chart of accounts, prepare monthly statements, flag unreconciled items, escalate unusual items, and submit completed files for CPA review.
2. Assign qualified people. Ask about accountant experience, training, software skills and reviewer qualifications, not just the sales deck. A dedicated bookkeeping team trained on your processes behaves very differently from a rotating pool.
3. Set up secure access and communication. See the security section below. Agree one channel, response times and escalation contacts up front.
4. Review performance and refine. In the first month, check whether reconciliations were on time, how many items needed rework, how many questions reached senior reviewers and whether procedures were followed. Documenting each client’s chart of accounts, categorisation rules and approval chain is what turns accounting practices into something a new team can follow.
Security, confidentiality and client disclosure
CPA firms hold sensitive financial and taxpayer information, so settle this part of the decision first.
Data protection. The IRS provides Publication 4557 as guidance for safeguarding taxpayer data. The AICPA notes that third-party outsourcing introduces risks a firm must identify, assess and manage. Before you start, establish:
- Role-based access and access-removal procedures
- Multi-factor authentication and encryption
- Secure document exchange and defined communication channels
- Confidentiality agreements
- Review and escalation procedures
Corient’s CPA outsourcing environment includes SOC 2 Type II controls, encryption, multi-factor authentication and alignment with IRS Publication 4557 requirements.
Disclosure and consent. Rules differ by state and can change, so treat this as a checklist for your own review:
- AICPA Code of Professional Conduct. The confidentiality provisions cover the use of third-party service providers. In general, a firm should tell clients that an outside provider may access their confidential information, and make sure that provider protects it. The AICPA publishes sample client disclosure language you can adapt.
- Tax return information. If the work touches tax return information, IRC §7216 and its regulations restrict disclosure and use without the client’s consent, and stricter requirements apply when the recipient is outside the United States.
- State boards of accountancy. Requirements vary by state. Check your board’s rules before sending client data to any provider.
- Engagement letters. Most firms update these to disclose that a third party may access client data, or obtain consent where required.
Whatever the disclosure rules say, your firm stays professionally responsible for the outsourced work product and for client data. That is why the vendor due diligence above applies either way. Confirm current requirements with your state board and legal counsel.
Onshore vs. offshore bookkeeping
| Factor | Onshore | Offshore |
|---|---|---|
| Location | US-based | Outside the US |
| Time-zone overlap | Usually high | May be limited; needs defined handoffs |
| Labour cost | Generally higher | Generally lower |
| Talent pool | US only | Broader international pool |
| Scalability | Limited by US hiring | More flexible capacity |
| Security diligence | Standard vendor due diligence | Enhanced due diligence, plus the consent questions above |
| Best fit | Proximity and direct collaboration | Scalable capacity and cost efficiency |
Never choose a provider on geography or price alone. Security, quality control, software compatibility, communication and review processes matter more than location. A well-managed offshore accounting team with documented review controls closes most of the gap, and at that point the difference is process, not geography. It also helps to understand the difference between a dedicated team and a staffing agency: see dedicated offshore team vs. staffing agency.
How to choose an outsourced bookkeeping partner
Use these questions before signing anything. The full version is in our vetting checklist.
- Can they work in our software? Corient supports QuickBooks, Xero, Sage and multiple professional tax platforms.
- Will the work stay under our brand? Corient’s model is white-label bookkeeping for CPA firms: the team works behind your brand as an extension of your firm.
- Who reviews the work before it reaches us? Look for defined quality control and senior review.
- Can capacity flex in tax season? Ask for specifics, not assurances.
- How is data protected? Ask about access controls, encryption, MFA, SOC reports and contract terms.
- Can we start with a pilot? A controlled pilot lets you test accuracy and turnaround before moving a larger portfolio.
- Can they grow with us? Corient’s CPA outsourcing services extend into tax preparation, financial reporting, audit and compliance support, and CFO and advisory work, which can save a second vendor transition.
Compare at least two or three providers against these questions. Provider types differ a lot: small-business bookkeeping platforms, freelancer marketplaces, regional firms and CPA-focused white-label specialists use different scope, pricing and review models, and only some are built to work behind a CPA firm’s brand.
How much does outsourced bookkeeping cost for CPA firms?
Comparing hourly rates alone gives the wrong answer. The right comparison is:
Outsourcing fee + your internal review time + vendor management time + rework
versus
Fully loaded in-house cost + software + workspace + recruiting + training + idle capacity.
Step 1: Work out your true in-house cost
The BLS reports a median annual wage of $50,670 for bookkeeping, accounting and auditing clerks (May 2025). Its Employer Costs for Employee Compensation data for June 2026 shows that wages and salaries make up about 70.0% of private-industry employer compensation costs, with benefits and other costs making up the remaining 30.0%. Dividing the wage by 0.70 gives a loaded cost:
- Median wage: $50,670
- Loaded annual cost: about $72,400 ($50,670 ÷ 0.70)
- Loaded monthly cost: about $6,030
The 70/30 split is an average across all private-industry jobs, so treat the result as an estimate rather than a quote. It still excludes software seats, workspace, recruiting, training, management time and the cost of covering the seat when someone leaves.
Step 2: Know the four pricing models
| Model | How it works | Best for |
|---|---|---|
| Hourly | You pay for hours worked | Fluctuating volume and short projects. Watch scope: costs can climb quickly if it is loose |
| Dedicated FTE | A named team member works only for your firm at a fixed monthly fee | Steady, year-round volume |
| Per-client monthly | A fixed fee per client for an agreed scope | Many clients with similar needs. Confirm exactly what is excluded |
| Project-based | A one-off fee | Cleanup and catch-up work. Ask for it as a separate line item |
Corient’s CPA outsourcing engagements can use dedicated FTE arrangements or per-return pricing, depending on workload and requirements.
Step 3: Add the costs people forget
For the outsourced option, include your internal review time, vendor management time, rework, and first-month transition effort (documenting processes and training the team).
Worked example: where does outsourcing break even?
Rather than guess at prices, work backwards from your in-house cost. These assumptions are illustrative, so replace them with your own:
- In-house cost: about $72,400 a year (from Step 1).
- Internal review: 2 hours a week. Vendor management: 1 hour a week. That is 156 hours a year at a blended internal cost of $60 an hour, or $9,360.
- Rework allowance: 5% of the outsourcing fee.
Break-even. Outsourcing costs the same as the in-house hire when (fee × 1.05) + $9,360 = $72,400. That gives a fee of about $60,000 a year, or $5,000 a month. Any dedicated-team quote well below $5,000 a month for the same scope leaves room for savings under these assumptions. A quote near or above it does not.
Two hypothetical quotes show how the gap works:
| In-house (median) | Quote at $3,000 a month | Quote at $4,000 a month | |
|---|---|---|---|
| Salary and benefits / annual fee | $72,400 | $36,000 | $48,000 |
| Internal review and management | not counted | $9,360 | $9,360 |
| Rework allowance (5%) | not counted | $1,800 | $2,400 |
| Annual total | $72,400 | $47,160 | $59,760 |
| Difference vs. in-house | about 35% lower | about 17% lower |
These fees are hypothetical, chosen to show the method, and are not market prices or Corient quotes. Two cautions apply. The in-house column is understated, because it leaves out software, workspace, recruiting and turnover, so real savings could be higher. And a dedicated FTE and a salaried hire are not identical, so confirm scope, review level and turnaround before comparing.
Which model fits which firm?
- Steady year-round volume: dedicated FTE.
- Strong seasonal spikes: flexible or hourly capacity, or a small dedicated core plus flex.
- A backlog of messy client books: project-based cleanup, then a monthly model.
- Unsure: a short pilot at fixed scope, so you learn your real review time and rework rate.
How to compare quotes
Ask every provider the same questions:
- What exactly is in the monthly fee, and what is billed separately?
- What happens to the price if volume rises 50%?
- Is cleanup quoted separately?
- How many hours of internal review should we budget?
- What are the service levels, and what happens if they are missed?
- Are there setup fees or minimum terms?
A quote without a deliverable list is not a quote.
The question most firms skip
Instead of asking only “how much does it cost?”, ask “what does it cost us not to outsource?” If senior accountants spend hundreds of hours a year on routine production, the opportunity cost can exceed the outsourcing fee. Each hour redirected to review, advisory or new client work has a value you can estimate from your own billing rates.
How to transition without disruption
Start with a pilot on clients with predictable workflows, documented rules, moderate transaction volume, compatible software and an internal reviewer who can give feedback.
- Week 1, document: map the workflow, assign responsibilities and write down client-specific rules.
- Week 2, set up: establish secure access, software permissions, communication and file sharing.
- Week 3, train: walk the team through sample transactions, reconciliations, reports and exception scenarios.
- Week 4, run and review: the team processes real work while your professionals review it.
Then measure accuracy, turnaround, rework, open queries, review effort and service-level performance. Once results are stable, move additional clients gradually. Successful outsourcing is not throwing work over a wall. It is building a repeatable production system.
People Also Ask:
What is outsourced bookkeeping for a CPA firm?
It is the practice of assigning routine bookkeeping production (reconciliations, categorisation, AP/AR and month-end close preparation) to an external team, while the CPA firm keeps client relationships, final review and professional responsibility.
Is outsourced bookkeeping safe for client data?
It can be, when the provider uses role-based access, encryption, multi-factor authentication and documented procedures aligned with IRS Publication 4557 and AICPA guidance on third-party risk. The firm remains responsible for verifying those controls before onboarding.
Do we need client consent to outsource bookkeeping?
Often you need at least disclosure, and sometimes consent, depending on your state board, the AICPA confidentiality rules and whether tax return information is involved. Confirm with your state board and legal counsel, and update your engagement letters accordingly.
Will my clients know their books are handled by an outsourced team?
Under a white-label model, the provider works in your software and under your brand, so clients deal only with your firm. That does not remove the disclosure and consent considerations above.
How long does onboarding take?
A well-run pilot follows the four-week plan above: document, set up, train, then run and review. Timing depends on how well your workflows are documented.
Can outsourced bookkeeping scale during tax season?
A good provider should be able to add capacity for seasonal spikes. Ask any prospective partner how they handled last season’s volume before you sign.
How much does outsourced bookkeeping cost?
It depends on the pricing model, provider location and scope. Compare the total (fee plus your review time, management time and rework) against the fully loaded cost of an in-house hire, about $72,400 a year at the BLS median wage. The cost section above shows a break-even calculation you can adapt.
Is offshore bookkeeping cheaper than hiring in the US?
Usually the fee is lower, but the saving depends on review effort, rework and management time. Do the full comparison rather than comparing rates.
Conclusion
Outsourced bookkeeping lets a CPA firm separate production from professional judgement, standardise recurring work and add capacity without adding headcount at the same rate. The provider matters: a cheap vendor that creates rework, communication problems or security concerns just becomes another management burden, while a technology-enabled, white-label partner can operate as a real extension of your firm.
If you want to see how this would map to your client base, talk to Corient’s CPA outsourcing team about a scoped pilot.
This article is for general information and is not legal, tax or professional advice. Confirm disclosure, consent and confidentiality requirements with your state board of accountancy and legal counsel. Wage and employer-cost figures are from the US Bureau of Labor Statistics.